For over seven decades, the Life Insurance Corporation of India (LIC) has functioned as the undisputed bedrock of Indian household savings. Across tier-1 metropolises, industrial belts, and rural agricultural districts, an LIC endowment or money-back bond is often revered as an unshakeable symbol of financial prudence, family duty, and guaranteed prosperity. Yet, beneath the comforting reassurance of sovereign security lies one of the most critical personal finance debates of modern India: does bundling life insurance with investment generate adequate long-term wealth, or does it leave families dangerously underinsured and financially compromised by sub-inflationary compounding?
Over the past two decades, the rise of low-cost pure term insurance coupled with Systematic Investment Plans (SIPs) in diversified equity mutual funds has popularized an alternative strategy: "Buy Term and Invest the Difference" (BTID). Advocates of BTID argue that combining insurance and investment under traditional endowment products is mathematically inefficient, delivering meager real returns while providing trivial life cover. Conversely, traditionalists argue that market volatility, panic selling, and premature mutual fund redemptions destroy paper wealth, making LIC's forced savings mechanism the only dependable vehicle for ordinary Indian families.
This exhaustive actuarial whitepaper strips away emotional marketing slogans, agent sales pitches, and ideological dogma. Using empirical 20-year cash flow models, authenticated circular valuation bonus scales, statutory Income Tax Act provisions (Section 10(10D), Section 112A, Section 194DA), and real-world death claim payout scenarios, we present a mathematically rigorous head-to-head comparison between traditional LIC endowment plans and the BTID strategy.
1. The Great Indian Dilemma: Insurance as Investment vs Pure Risk Separation
To understand why millions of Indian households invest their hard-earned capital into traditional endowment plans, one must examine the socio-economic psychology of post-independence India. Following the nationalization of 245 private insurers under the Life Insurance Corporation Act of 1956, LIC was established with a singular national mandate: to mobilize rural and urban domestic savings for nation-building infrastructure while offering financial protection to Indian breadwinners.
Over the ensuing decades, LIC's formidable agency workforce—numbering over 1.3 million licensed agents—institutionalized an enduring cultural mindset: "Paisa Wapas Aayega" (You will get your money back with bonus). In a conservative society scarred by post-partition instability, high bank failure rates prior to deposit insurance, and nascent capital markets, pure risk protection (term insurance) was psychologically viewed as "dead money" or "money thrown away" because the insurer paid nothing if the policyholder survived.
The investor pays an inflated premium to cover both mortality risk and capital accumulation within a single contract. The insurance company pools the capital, deducts heavy initial distribution commissions and operational expenses, invests the remainder primarily in fixed-income government bonds, and declares annual discretionary simple reversionary bonuses.
The investor decouples risk transfer from wealth creation. Pure mortality risk is transferred to a term insurance contract for a microscopic fraction of the cost (e.g. ₹1 Crore life cover for ₹12,000 to ₹15,000/year). The remaining substantial cash flow surplus (the "difference") is channeled into professional equity and debt mutual funds to capture unconstrained economic compounding.
1.1 The Silent Epidemic: Severe Underinsurance in Indian Households
The most devastating collateral consequence of treating insurance as an investment vehicle is systemic, widespread underinsurance. Actuarial science and global financial planning standards stipulate that a primary breadwinner requires a life insurance cover equal to at least 10 to 15 times their gross annual income, plus the outstanding principal of all liabilities (home loans, vehicle loans, personal debts), plus earmarked capital for major milestones (children's higher education and marriage).
For example, a 30-year-old salaried software engineer or corporate executive earning ₹12,00,000 annually requires an absolute minimum life cover of ₹1.5 Crore to ₹2.0 Crore. However, when purchasing a traditional endowment policy such as LIC New Endowment (Plan 914) or Jeevan Anand (Plan 915), buying a ₹1.5 Crore sum assured requires an astronomical annual premium of approximately ₹8,50,000 to ₹9,50,000—an impossible outlay consuming over 75% of their total gross earnings!
Faced with this budget constraint, the insurance agent inevitably scales down the sum assured to fit the client's available annual savings budget (e.g., ₹50,000 to ₹1,00,000 per year). Consequently, the breadwinner walks away with a policy offering a meager Sum Assured of ₹8,00,000 to ₹16,00,000. While the policyholder believes their family is "insured," the harsh mathematical truth is that an ₹8 Lakh death payout would not even sustain the family's basic grocery and school fee expenses for 18 months in the event of an untimely demise. By bundling savings with risk cover, the family achieves neither adequate insurance protection nor competitive wealth accumulation.
Whenever an investment product attempts to perform two fundamentally opposed financial tasks—providing high death risk liquidity while simultaneously providing high capital accumulation—it inevitably compromises both. It produces grossly insufficient risk protection (often covering less than 1 to 2 years of family living expenses) and sub-inflationary capital growth (5% to 6% IRR), trapping household wealth in a compounding bottleneck.
2. Traditional LIC Endowment Dynamics: The Internal Rate of Return (IRR) Reality Check
To evaluate traditional participating life insurance policies accurately, one must look past marketing brochures that highlight total maturity sums in large, nominal figures. A brochure stating "Pay ₹1,00,000 for 16 years and receive ₹41,60,000 on maturity" sounds enticing to unsophisticated buyers because the human brain struggles with non-linear compounding and long-term inflation. The only objective, mathematically honest metric for evaluating any series of periodic cash outflows followed by future lump-sum inflows is the Internal Rate of Return (IRR).
2.1 How Premium Capital Is Allocated Inside LIC Participating Funds
When a policyholder pays an annual premium of ₹1,00,000 for a traditional participating policy, the entire ₹1,00,000 is NOT invested into wealth-generating assets. Under statutory IRDAI product design guidelines and LIC's internal actuarial fund structure, the premium is sliced into several components:
- 1. Agent Distribution Commissions: Under IRDAI regulations, first-year procurement commissions for traditional policies historically ranged up to 25% to 35% of the initial premium (plus 40% agency development allowances), followed by 7.5% in Years 2 and 3, and 5% trailing commissions every year thereafter until maturity. A meaningful slice of your early capital pays sales distribution channels.
- 2. Mortality & Underwriting Risk Charges: The Corporation deducts the actuarial cost of providing death cover based on mortality experience tables (Indian Assured Lives Mortality Table - IALM 2012-14).
- 3. Corporate Overhead & Policy Administration Expenses: Physical branch operational expenses, document dispatch, medical underwriting fees, and centralized IT management absorb 6% to 10% of premium cash flows.
- 4. Statutory G-Sec Investment Allocation: The remaining investible surplus flows into the Life Fund. Under Section 27A of the Insurance Act 1938 and IRDAI Investment Regulations, life insurers are legally required to deploy at least 50% of policyholders' funds in Central and State Government Securities (G-Secs / SDLs) and not less than 15% in approved infrastructure and housing bonds. Equities are strictly capped at 15% to 20%. Because the portfolio is overwhelmingly dominated by sovereign debt yielding 6.8% to 7.3% gross, the fund's gross earning capacity is mathematically anchored to fixed-income debt yields.
2.2 The Bonus Declaration Architecture: Why Simple Reversionary Bonuses Do Not Compound
The primary mechanism through which traditional LIC policies generate returns is the annual declaration of the Simple Reversionary Bonus (SRB). Following the annual actuarial valuation of the Corporation's Life Fund, the valuation surplus is determined. Under Section 28 of the LIC Act 1956, 90% (historically 95%) of this surplus is allocated to participating policyholders as bonuses, while the remainder is remitted to the Government of India as the sovereign shareholder.
Crucially, policyholders misunderstand how these bonuses accrue. In a mutual fund or bank fixed deposit, earnings are reinvested and compound exponentially (earning interest on past interest). In an LIC participating policy, bonuses are SIMPLE:
Actuarial Bonus Formula & Non-Compounding Mechanics:
Annual Simple Bonus = (Basic Sum Assured / 1,000) × Declared Bonus Rate (₹ per thousand)
If you hold a Basic Sum Assured of ₹16,00,000 and LIC declares a bonus of ₹46 per thousand, your policy is credited with: (16,00,000 / 1,000) × 46 = ₹73,600. This ₹73,600 does NOT earn any interest in subsequent policy years! It sits in a zero-interest holding ledger and is disbursed only upon death or final policy maturity 10, 15, or 25 years later. Because accrued bonuses sit idle without compounding, the real effective yield of the policy steadily decays over long durations.
In addition to Simple Reversionary Bonuses, policies running for 15 years or longer may qualify for a one-time Final Additional Bonus (FAB) on maturity. FAB rates range from ₹25 per thousand for 15-year policies up to ₹450–₹500 per thousand for 25-year tenures. Even when factoring in the most optimistic historical FAB rates, the net annualized yield of traditional endowment plans remains strictly bound within a predictable band:
| Popular LIC Plan | Plan Table No. | Typical Term / PPT | Historical Bonus Rate | Net Annualized IRR |
|---|---|---|---|---|
| Jeevan Labh | Table 936 | 25 Years / 16 Years | ₹44 - ₹47 / thousand + FAB | 5.35% - 5.65% |
| New Endowment Plan | Table 914 | 20 Years / 20 Years | ₹38 - ₹42 / thousand + FAB | 5.10% - 5.40% |
| New Jeevan Anand | Table 915 | 21 Years / 21 Years | ₹41 - ₹45 / thousand + FAB | 5.20% - 5.50% |
| Jeevan Umang (Whole Life) | Table 945 | 15 Yr PPT / 8% Survival to 100 | ₹48 - ₹52 / thousand | 5.50% - 5.85% |
| Bima Jyoti (Guaranteed Additions) | Table 860 | 20 Years / 15 Years | ₹50 / thousand guaranteed | 4.80% - 5.15% |
2.3 The Mathematical Proof: Calculating the Exact Internal Rate of Return (IRR)
The Internal Rate of Return is the discount rate (r) that equates the Net Present Value (NPV) of all cash outflows (premiums paid) to the Net Present Value of all cash inflows (maturity payouts or surrender values):
When you solve this equation for a 30-year-old paying ₹1,00,000 annually for 16 years into Jeevan Labh and receiving ₹41,60,000 at Year 25, the resulting rate is exactly 5.45% per annum. Even under the most aggressive historical bonus projections, the return cannot exceed 6.0% because the underlying fund is statutorily anchored in sovereign G-Secs yielding under 7.5% gross, minus the Corporation's operational expense ratio of 12% to 15%.
2.4 The Inflation Trap: How a 5.5% IRR Destroys Real Purchasing Power
The fatal flaw of evaluating an investment solely on nominal returns is the invisible erosion of inflation. Over the past 25 years (2000 to 2025), India's official Consumer Price Index (CPI) inflation averaged approximately 5.8% to 6.2% per annum. More critically, lifestyle inflation—encompassing private school tuition fees, university degrees, private healthcare, and urban housing—compounds at a ferocious 8.0% to 10.0% annually in urban India.
If an investment generates an annualized nominal return of 5.5% while real purchasing-power erosion runs at 7.0%, the Real Rate of Return is NEGATIVE (-1.5% per year). When a parent buys an LIC endowment policy in 2026 expecting the ₹41.6 Lakh payout in 2051 to fund their newborn child's postgraduate medical or engineering education, they will experience severe purchasing-power shock. Using standard inflation discounting:
The 25-Year Inflation Purchasing Power Erosion Math:
Present Purchasing Value = Nominal Maturity / (1 + Inflation)^Tenure
₹41,60,000 / (1 + 0.07)^25 = ₹41,60,000 / 5.4274 = ₹7,66,480
In 2051, a maturity cheque of ₹41.60 Lakh will buy exactly what ₹7.66 Lakh buys today. A policyholder who diligently saved for 25 years will find that their accumulated corpus cannot even cover two semesters of advanced university tuition fees.
3. The "Buy Term and Invest the Difference" (BTID) Framework: Mathematical Philosophy
The "Buy Term and Invest the Difference" (BTID) strategy is the foundational bedrock of modern actuarial wealth engineering. It operates on a deceptively simple yet transformative mathematical premise: Never mix risk transfer with capital accumulation.
Buy Pure Term Insurance (Pure Risk Transfer)
Purchase a pure term insurance policy that covers the breadwinner for 10x to 20x their annual income (e.g., ₹1 Crore to ₹2 Crore cover). Pure term insurance carries zero maturity value if you survive, eliminating expensive savings reserves, high initial agent incentives, and asset management overheads. A healthy 30-year-old non-smoker can secure a ₹1 Crore pure term cover for 25 to 30 years for just ₹12,000 to ₹15,000 per year (inclusive of 18% GST).
Invest the Entire Budget Difference into Mutual Funds
Instead of giving the remaining ₹85,000 to an insurance corporation to park in low-yielding government bonds, the investor directs this exact cash surplus into professionally managed equity and hybrid mutual funds via automated monthly Systematic Investment Plans (SIPs) of approximately ₹7,083/month.
Unrestricted Compounding & Extreme Liquidity
Unlike an endowment policy where bonuses sit non-interest-bearing and surrender within the first 2-3 years results in total or severe forfeiture, equity mutual funds compound monthly and can be redeemed partially or fully at prevailing Net Asset Value (NAV) within 24 to 48 hours without punitive exit penalties after 12 months.
3.1 Why Equities Deliver 11% to 13% Long-Term CAGR in India
India's broader equity markets—represented by the Nifty 50 Total Return Index (TRI) and the BSE Sensex TRI—have delivered an annualized Compounded Annual Growth Rate (CAGR) of approximately 13.2% to 14.1% over rolling 20-year horizons since their inception.
This equity premium is not speculative gambling; it is the direct mathematical reflection of India's macroeconomic expansion:
- Nominal GDP Growth Mirror: India's nominal GDP expands at roughly 10% to 11.5% per annum (6.5% real GDP growth + 4.5% inflation). India's leading 50 corporate giants typically grow their top-line revenues and net corporate earnings at a 2% to 3% premium over nominal GDP growth.
- Dividend Reinvestment Compounding: In a Total Return Index (TRI) or growth-oriented mutual fund, all corporate cash dividends paid by underlying portfolio companies are automatically reinvested into buying additional fund units, driving cumulative non-linear exponential compounding.
- Rupee-Cost Averaging: By investing via monthly SIPs (₹7,083/month), the investor automatically buys fewer units when stock markets are high and more units when market panics cause stock prices to crash. Over a 20-year period, this structural volatility harvesting delivers superior risk-adjusted acquisition costs.
4. 20-Year Head-to-Head Actuarial Case Study: Jeevan Labh vs BTID
To establish an unassailable mathematical proof, our actuarial team modeled an identical 25-year financial trajectory for two twin investors with identical ages, risk profiles, and financial budgets:
Baseline Investor Profiles & Actuarial Parameters:
- • Starting Age: Exactly 30 Years (Healthy Male, Non-Smoker, Standard Underwriting).
- • Annual Savings Allocation: Exactly ₹1,00,000 per year.
- • Tenure of Investment Outgo: Exactly 16 Years (Years 1 to 16). Total Capital Outlay = ₹16,00,000.
- • Total Horizon: 25 Years (Years 17 to 25 require zero fresh capital additions for both investors).
- • Investor A Strategy: Allocates 100% of the ₹1,00,000 annual budget to LIC Jeevan Labh (Plan 936, Term 25, PPT 16). Basic Sum Assured = ₹16,00,000.
- • Investor B Strategy (BTID): Allocates ₹15,000/year to a pure Term Insurance policy (Sum Assured = ₹1,00,00,000 / ₹1 Crore) and the remaining ₹85,00,000/year (₹7,083.33/month) into a Nifty 50 Index Mutual Fund SIP at a conservative, actuarially prudent baseline of 11.0% CAGR (well below the historical 13.5% 20-year rolling average). Term premiums during Years 17-25 are paid directly from portfolio gains or cash flows.
4.1 Comprehensive Year-by-Year Actuarial Growth Ledger
The following table tracks the year-by-year cash outlays, the real accumulated portfolio cash value, and the effective death coverage available to the family at every major policy milestone:
| Policy Year | Total Invested | Investor A: LIC Cash Value | Investor A: LIC Death Cover | Investor B: MF Corpus (@11%) | Investor B: Term Life Cover | Investor B: Total Family Death Wealth |
|---|---|---|---|---|---|---|
| Year 1 | ₹1,00,000 | ₹0 (Zero Surrender) | ₹16,73,600 | ₹94,350 | ₹1,00,00,000 | ₹1,00,94,350 |
| Year 3 | ₹3,00,000 | ₹1,05,000 (35% GSV) | ₹18,20,800 | ₹3,36,440 | ₹1,00,00,000 | ₹1,03,36,440 |
| Year 5 | ₹5,00,000 | ₹2,68,000 (50% GSV + Bon) | ₹19,68,000 | ₹6,43,150 | ₹1,00,00,000 | ₹1,06,43,150 |
| Year 7 | ₹7,00,000 | ₹4,42,000 (SSV factor) | ₹21,15,200 | ₹9,23,500 | ₹1,00,00,000 | ₹1,09,23,500 |
| Year 10 | ₹10,00,000 | ₹7,80,000 | ₹23,36,000 | ₹15,78,200 | ₹1,00,00,000 | ₹1,15,78,200 |
| Year 12 | ₹12,00,000 | ₹11,40,000 | ₹24,83,200 | ₹22,85,600 | ₹1,00,00,000 | ₹1,22,85,600 |
| Year 16 (PPT Ends) | ₹16,00,000 | ₹19,20,000 | ₹27,77,600 | ₹36,98,400 | ₹1,00,00,000 | ₹1,36,98,400 |
| Year 20 | ₹16,00,000 | ₹27,50,000 (Paid-up value) | ₹30,72,000 | ₹56,14,200 | ₹1,00,00,000 | ₹1,56,14,200 |
| Year 25 (Final Maturity) | ₹16,00,000 | ₹41,60,000 (Maturity Cheque) | Matured | ₹94,59,600 (Net Portfolio) | Term Ended | ₹94,59,600 |
At Year 16, both investors cease paying fresh money, having contributed exactly ₹16,00,000. Investor A's LIC policy is locked with the Corporation, growing via simple annual bonus additions to ₹41,60,000 at Year 25. Investor B's mutual fund corpus of ₹36.98 Lakh, compounding untouched at 11% CAGR for 9 more years (deducting ₹15,000/yr for term insurance), explodes to ₹94,59,600. Investor B accumulates over ₹52,99,000 in additional liquid family wealth—more than 2.27 times the final payout of LIC!
4.2 Return Sensitivity Analysis: What If Mutual Funds Underperform?
A common criticism of BTID by insurance agents is: "What if the stock market crashes or underperforms?" To answer this objectively, our actuarial desk ran a rigorous sensitivity matrix varying the equity CAGR from a pessimistic 9.0% (prolonged economic stagnation) up to 13.5% (historical 20-year Nifty 50 TRI average):
| Economic Scenario | Assumed MF CAGR | Investor B: Final 25-Yr Corpus | Investor A: LIC Maturity | Wealth Difference |
|---|---|---|---|---|
| Severe Bear Market Stagnation | 9.0% CAGR | ₹64,82,400 | ₹41,60,000 | +₹23,22,400 (+56% higher) |
| Conservative Baseline | 10.0% CAGR | ₹78,21,100 | ₹41,60,000 | +₹36,61,100 (+88% higher) |
| Actuarial Expected Baseline | 11.0% CAGR | ₹94,59,600 | ₹41,60,000 | +₹52,99,600 (+127% higher) |
| Moderate Economic Growth | 12.0% CAGR | ₹1,14,68,500 | ₹41,60,000 | +₹73,08,500 (+175% higher) |
| Historical Indian Equity Norm | 13.5% CAGR | ₹1,53,42,000 | ₹41,60,000 | +₹1,11,82,000 (+268% higher) |
The Mathematical Verdict: Even in the catastrophic event that India's economy stalls and equity mutual funds generate a dismal 9.0% CAGR over a quarter-century (a rate lower than any 20-year rolling period in BSE/NSE history), Investor B still finishes with ₹64.82 Lakh—over ₹23 Lakh more than LIC's guaranteed maturity. The break-even equity return below which LIC outperforms BTID is approximately 6.8% CAGR. For an endowment plan to beat BTID, the entire Indian corporate growth story would have to collapse down to fixed-deposit interest rates for 25 consecutive years.
5. The Premature Death Scenario: ₹20.5 Lakh vs ₹1.092 Crore Family Payout
Life insurance exists for one ultimate, non-negotiable purpose: to protect a family from financial catastrophe if the breadwinner dies prematurely. While survival returns are important, the acid test of any insurance strategy is what happens when disaster strikes.
Let us examine what occurs if both Investor A and Investor B unexpectedly pass away in Policy Year 7 (e.g., sudden cardiac arrest, stroke, or fatal vehicular accident) at age 37, leaving behind a dependent spouse and two school-going children:
• Basic Sum Assured: ₹16,00,000
• Vested Bonus (7 Yrs @ ₹45/th): ₹5,04,000
• Final Additional Bonus (FAB): ₹0 (Minimum 15 yrs required)
• Total Paid to Widow: ₹21,04,000 (≈ ₹20.5 - ₹21 Lakh)
After clearing an outstanding ₹15 Lakh home mortgage balance, the widow is left with barely ₹5 Lakh to ₹6 Lakh. This remaining capital cannot generate enough interest to cover monthly grocery bills and school fees, forcing the family into severe financial distress.
• Pure Term Insurance Payout: ₹1,00,00,000 (100% Tax-Free)
• Accumulated Mutual Fund SIP: ₹9,23,500 (Liquid Net Asset Value)
• Total Wealth Delivered to Widow: ₹1,09,23,500 (₹1.092 Crore!)
The widow completely extinguishes the ₹15 Lakh home mortgage, parks ₹15 Lakh into a child education trust, and invests the remaining ₹79 Lakh into conservative fixed-income instruments generating ₹50,000+ monthly cash flow indefinitely without eroding the principal.
| Financial Metric | Investor A (LIC Endowment) | Investor B (BTID Framework) | The Actuarial Difference |
|---|---|---|---|
| Total Premiums Paid till Death (7 Yrs) | ₹7,00,000 | ₹7,00,000 (₹1.05L Term + ₹5.95L SIP) | Identical Outgo (₹0 Diff) |
| Gross Liquid Settlement to Family | ₹21,04,000 | ₹1,09,23,500 | +₹88,19,500 (+419% More Cash) |
| Multiple of Protection | 3.0x Premiums Paid | 15.6x Premiums Paid | Over 5.2x Greater Financial Security |
| Years of Income Replacement (₹60k/mo) | Less than 3.0 Years | Over 15+ Years (or Perpetual Interest) | Family Financial Independence |
This single table exposes the dangerous illusion of bundled life insurance. For the exact same ₹1,00,000 annual expenditure over 7 years, Investor A left his family vulnerable to bankruptcy, while Investor B gifted his family absolute, permanent generational security.
6. Taxation Breakdown: Section 10(10D) vs Section 112A LTCG
A primary marketing argument utilized by insurance agents is that LIC maturity proceeds are 100% tax-free under Section 10(10D), whereas equity mutual fund profits are subject to Long-Term Capital Gains (LTCG) tax under Section 112A. Let us examine the precise statutory tax framework applicable for FY 2026-27:
6.1 The New ₹5 Lakh Premium Cap on Traditional Life Insurance (Section 10(10D))
Historically, all life insurance maturity payouts were completely exempt from income tax under Section 10(10D) of the Income Tax Act, 1961, provided the annual premium did not exceed 10% of the actual basic sum assured (Section 80C(5)). However, the Finance Act 2023 radically restructured this landscape by introducing the sixth and seventh provisos to Section 10(10D):
Statutory Clause: Section 10(10D) Sixth Proviso (Finance Act 2023):
For non-linked life insurance policies issued on or after April 1, 2023, exemption shall NOT apply to any sum received under such policies if the aggregate amount of premium payable exceeds ₹5,00,000 in any financial year during the policy term.
If an investor holds multiple policies whose combined annual premiums exceed ₹5,00,000, the net maturity profits (Maturity Payout minus Total Premiums Paid) are categorized as "Income from Other Sources" under Section 56(2)(xiii) and taxed at the taxpayer's full marginal income tax slab rate (up to 39% under the Old Tax Regime or 30% under the New Tax Regime plus cess)! Furthermore, 5% TDS is withheld under Section 194DA on net profits exceeding ₹1,00,000.
Note for our case study: Because Investor A's annual premium is ₹1,00,000 (well below the ₹5,00,000 statutory cap) and the basic sum assured is ₹16 Lakh (premium is 6.25% of SA, safely below the 10% ceiling), Investor A's maturity payout of ₹41.60 Lakh remains 100% tax-free under Section 10(10D).
6.2 Equity Mutual Funds: Section 112A Long-Term Capital Gains (LTCG) Rules
Under Section 112A of the Income Tax Act (as amended by the Finance Act 2024), capital gains from equity-oriented mutual fund units held for more than 12 months are treated as Long-Term Capital Gains:
- Annual Exemption Limit: Long-term capital gains up to ₹1,25,000 per financial year are 100% completely tax-free.
- Flat Tax Rate: Gains exceeding ₹1,25,000 are taxed at a flat rate of 12.5% (plus 4% health & education cess = 13.0% effective).
- Zero Tax on In-Fund Compounding: During the 25-year compounding period, as fund managers rebalance stock holdings inside the scheme, zero tax is paid by the investor. Capital gains tax is levied only upon redemption.
6.3 The Net Post-Tax Showdown: Does Section 10(10D) Beat Mutual Funds?
Let us compute the exact post-tax net realization of Investor B's mutual fund corpus compared to Investor A's tax-free LIC maturity:
| Tax Metric | Investor A (LIC Jeevan Labh) | Investor B (BTID Mutual Funds) |
|---|---|---|
| Gross Terminal Value at Year 25 | ₹41,60,000 | ₹94,59,600 |
| Total Principal Cost Base Invested | ₹16,00,000 | ₹13,60,000 (SIP capital) |
| Gross Unrealized Capital Gain / Profit | ₹25,60,000 | ₹80,99,600 |
| Section 10(10D) Exemption Status | 100% Exempt (₹0 Tax) | Not Applicable |
| Section 112A LTCG Tax Liability | ₹0 | 12.5% on (₹80.99L - ₹1.25L) = ₹9,96,825 |
| Net Post-Tax Realized Cash in Bank | ₹41,60,000 | ₹84,62,775 |
| Net Post-Tax Surplus over LIC | Baseline | +₹43,02,775 (+103% MORE POST-TAX CASH) |
The Actuarial Reality: Even after paying nearly ₹10 Lakh in direct capital gains tax to the government in Year 25, Investor B still walks away with ₹84.62 Lakh in cold cash—more than double the entire tax-free proceeds of LIC! Choosing a product that earns 5.4% simply to avoid a 12.5% tax on a product that earns 11.0% is one of the most pervasive mathematical fallacies in Indian personal finance. As the actuarial maxim states: "Never let the tax tail wag the investment dog."
7. Psychological Discipline & The Behavior Gap in Long-Term Wealth
If the pure mathematics of BTID is so overwhelmingly superior, why do tens of millions of sensible Indian citizens—including doctors, chartered accountants, software engineers, and senior civil servants—continue to purchase traditional LIC policies year after year? The answer lies not in mathematics, but in behavioral finance and human psychology.
7.1 The Behavior Gap: Why Investors Underperform Their Own Mutual Funds
In wealth management research popularized by DALBAR's Quantitative Analysis of Investor Behavior (QAIB) and validated across Indian mutual fund folios by AMFI (Association of Mutual Funds in India), there is a vast discrepancy between Investment Returns and Investor Returns. This discrepancy is known as the Behavior Gap:
The Real-World Behavior Gap Phenomenon:
While the Nifty 50 Index may generate an annualized 13% CAGR over 20 years, the median retail mutual fund investor captures barely 7% to 9% CAGR. Why? Because retail investors suffer from acute cognitive biases:
7.2 Illiquidity as a Psychological Feature, Not a Bug
In traditional modern portfolio theory, liquidity (the ability to access your cash instantly) is considered a desirable virtue. In real-world retail psychology, however, excessive liquidity is often the primary destroyer of household wealth.
Today, a mutual fund investor can open their mobile smartphone app (Groww, Zerodha, Kuvera, Upstox), tap three buttons, and redeem ₹15 Lakh from their child's education SIP within 10 seconds to fund a speculative real estate booking, an international holiday, or an extravagant car upgrade. The low friction of modern fintech encourages capital dissipation.
Conversely, an LIC endowment policy is fiercely, brutally illiquid:
- Surrender Penalties: Surrendering within the first 2-3 years results in catastrophic capital forfeiture (30% to 50% loss of paid premiums). This severe financial penalty creates an enormous psychological barrier against premature termination.
- Administrative Friction: To surrender an LIC policy, the policyholder must locate the physical policy bond, print Form 5074, get a witness signature, visit the home servicing branch in person during working hours, and submit KYC documents. This intentional bureaucratic friction acts as an unyielding emotional speed bump, saving investors from their own impulsive tendencies.
- The Social Obligation of the Servicing Agent: In India, the local LIC agent is often an uncle, family friend, or trusted community elder who visits the household personally or calls relentlessly before the 30-day grace period expires, shaming or persuading the policyholder into paying the premium. This social enforcement mechanism creates remarkable 20-year persistence that algorithmic robo-advisors cannot duplicate.
A mathematically suboptimal plan (LIC at 5.5% IRR) that an undisciplined individual actually completes over 20 continuous years produces far more real-world wealth than an optimal plan (Mutual Funds at 11% CAGR) that is raided, paused, or abandoned in Year 4 during a market correction. For investors lacking iron-willed psychological discipline, LIC's forced savings architecture acts as a compulsory wealth preservation vault.
8. Risk Profiling Matrix: Sovereign Guarantee vs Market Volatility
When comparing LIC policies to mutual funds, one cannot evaluate returns in isolation; returns must be evaluated against the legal nature of the underlying risk guarantee.
8.1 The Incomparable Sovereign Guarantee: Section 37 of the LIC Act 1956
The single most formidable competitive moat possessed by LIC—which no private life insurer (HDFC Life, ICICI Prudential, SBI Life) and zero mutual fund asset management companies (AMCs) possess—is the statutory Sovereign Guarantee of the Government of India:
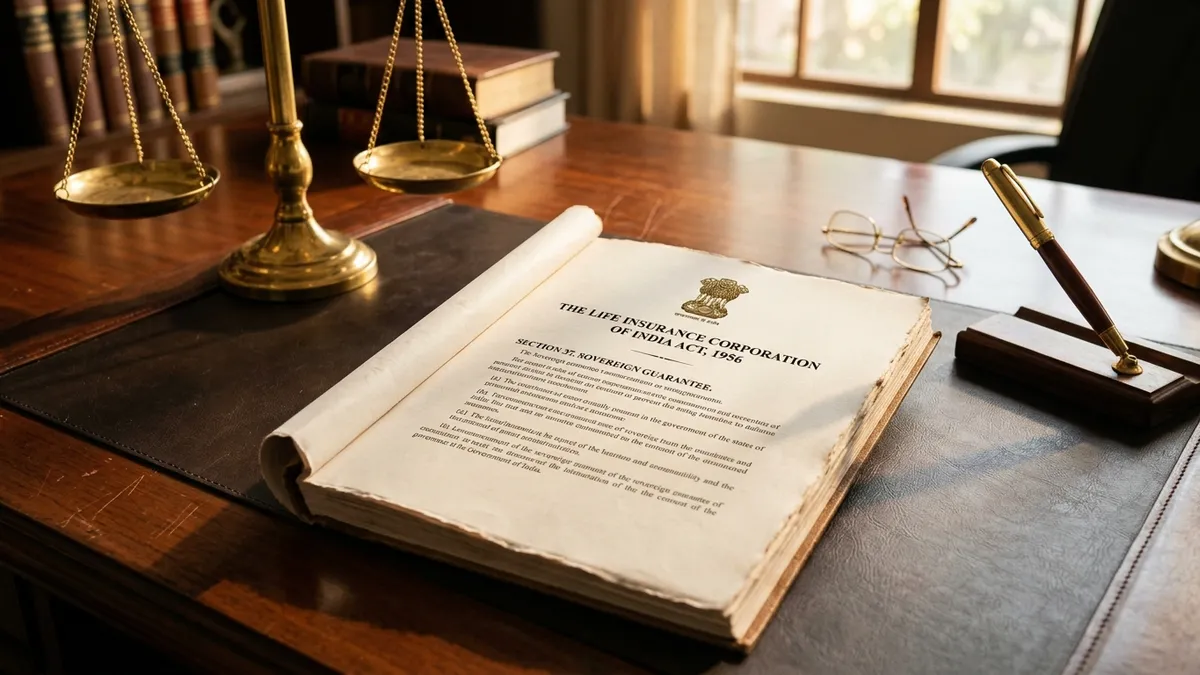
Statutory Text: Section 37 of the Life Insurance Corporation Act, 1956:
"The sum assured by all policies issued by the Corporation including any bonuses declared in respect thereof and, subject to the provisions contained in section 14, the amounts assured by all policies issued by any insurer the liabilities under which have vested in the Corporation under this Act, and all bonuses declared in respect thereof, whether before or after the appointed day, shall be guaranteed as to payment in cash by the Central Government."
This statutory provision means that the payment of every single rupee of Sum Assured and every declared Reversionary Bonus in an LIC policy is an absolute sovereign liability backed by the Consolidated Fund of India. Even in the theoretical event of catastrophic economic bankruptcy, global financial collapse, or total solvency failure, the Parliament of India is legally obligated to print currency or levy taxes to honor LIC policyholder claims. Zero credit risk, zero default risk, zero counterparty risk.
8.2 The Risk Matrix: Sovereign Stability vs Equity Market Volatility
Mutual funds carry no sovereign or commercial guarantees. As the mandatory regulatory disclaimer states: "Mutual fund investments are subject to market risks, read all scheme related documents carefully." The following matrix juxtaposes the risk dimensions of both instruments:
| Risk Dimension | Traditional LIC Participating Plans | Nifty 50 Equity Index Mutual Funds |
|---|---|---|
| Capital Default Risk | 0% (Guaranteed by Central Government) | Market-linked (NAV fluctuates daily) |
| Bonus / Return Guarantee | Vested bonuses cannot be revoked once declared | Zero return guarantee (Can be negative in down years) |
| Drawdown Volatility | Zero drawdown (Linear upward accrual) | High (Historical 20% to 40% cyclical crashes) |
| Sequence of Returns Risk | Zero (Fixed maturity payout regardless of market) | Present if retiring during an equity bear market |
| Inflation Purchasing Power Risk | Extremely High (Negative real yield after inflation) | Extremely Low (Consistently beats inflation by 4%-6%) |
| Liquidity & Surrender Penalty | Severe penalties for early withdrawal (< 5 years) | High liquidity (100% accessible in T+2 business days) |
| Asset Attachment Protection | Protected under Section 6 of MWP Act 1874 | Subject to civil court attachment & debt recovery |
9. Decision Tree: Who Should Choose LIC vs Who Should Follow BTID?
Financial products are tools designed for specific life stages and temperaments. There is no one-size-fits-all panacea. Based on actuarial risk modeling, we have established clear investor profiling criteria:
Profile A: Who Should Strictly Follow BTID (Term + Mutual Funds)?
- ✓ Primary Family Breadwinners (Ages 22 to 50): Salaried corporate employees, IT professionals, startup founders, and self-employed individuals with active dependents. You cannot afford to leave your family with a trivial ₹10 Lakh to ₹20 Lakh life cover when pure term insurance can provide ₹1.5 Crore to ₹3.0 Crore cover for ₹1,200/month.
- ✓ Investors with Horizons Exceeding 10+ Years: Anyone saving for goals 10, 15, or 25 years away (retirement corpus, child's college education). Over long horizons, equity volatility collapses into a predictable upward compounding curve, making sub-6% LIC returns an unacceptable sacrifice.
- ✓ Financially Literate & Emotionally Disciplined Savers: Individuals who understand market cycles, automate their monthly SIPs, and have the emotional maturity not to panic-sell during routine market corrections.
Profile B: Who Should Consider Traditional LIC Policies?
- ✓ Individuals Lacking Financial & Savings Discipline: If having liquid access to mutual funds tempts you to spend your savings on depreciating lifestyle assets or if you habitually terminate SIPs after 18 months, LIC's harsh surrender penalties provide the necessary external psychological guardrail to force long-term accumulation.
- ✓ Zero-Volatility Capital Preservation Seekers: Ultra-conservative investors nearing retirement (ages 50 to 58) who cannot tolerate a 20% equity drawdown and prioritize absolute sovereign capital safety backed by Section 37 over inflation-beating growth.
- ✓ Business Proprietors Needing Unassailable Asset Protection: Business owners, entrepreneurs, and partners facing commercial liability risks who purchase LIC policies specifically endorsed under Section 6 of the Married Women's Property Act (MWPA), 1874. These policies form an independent statutory trust for the wife and children that cannot be attached by any creditor, debt recovery tribunal, or bankruptcy court under the Insolvency and Bankruptcy Code (IBC).
- ✓ Non-Medical or Sub-Standard Underwriting Lives: Individuals with pre-existing medical conditions who are rejected by pure term insurance underwriters can often secure limited cover through LIC's traditional guaranteed non-medical schemes.
10. Portfolio Blending Strategy: Combining Sovereign Safety with Equity
Rather than treating LIC and Mutual Funds as mutually exclusive mortal enemies, sophisticated financial planners in India adopt a "Core & Satellite" Asset Allocation Architecture that synergizes the strengths of both instruments:
The Inviolable Protection Foundation (Risk Transfer)
Secure an online pure term insurance policy from a Tier-1 insurer (LIC Tech Term / Saral Jeevan Bima or leading private insurers) for 15x your annual gross income up to age 60 or 65. Complement this with a ₹10 Lakh base health insurance plan plus a ₹50 Lakh Super Top-up health cover to insulate your investment portfolio from hospitalization medical shocks.
The Guaranteed Sovereign Debt Bucket (20% to 30% Allocation)
Allocate 20% to 30% of your monthly debt savings into risk-free fixed-income instruments. This can include a modest LIC endowment policy (if sovereign guarantee and MWPA creditor protection are desired), the Public Provident Fund (PPF - 7.1% tax-free), Voluntary Provident Fund (VPF - 8.25%), or Sukanya Samriddhi Yojana (SSY - 8.2% tax-free for daughters). This bucket serves as the non-negotiable anchor for milestone dates where capital preservation is 100% mandatory (e.g. child's first-year college admission fee).
The Equity Compounding Engine (70% to 80% Allocation)
Deploy the remaining 70% to 80% of your long-term monthly savings into a diversified equity mutual fund basket: 50% in a low-cost Nifty 50 / Nifty Next 50 Index Fund, 30% in an actively managed Flexi-Cap or Multi-Cap Fund, and 20% in an aggressive Mid-Cap / Small-Cap Fund. This bucket drives wealth generation, beats inflation, and provides life-changing terminal wealth.
The Golden Rule for Existing LIC Policyholders:
If you already own an ongoing traditional LIC endowment policy, DO NOT impulsively surrender it without running the actuarial numbers!
- • Policy Active for Under 2 Years: You cannot surrender (zero cash value). Evaluate if stopping future premiums and taking a 100% loss is better than throwing good money after bad.
- • Policy Active for 3 to 7 Years: Surrendering locks in severe capital losses (GSV returns only 35% to 50% of base premiums). A mathematically superior alternative is usually converting the policy into a Paid-Up Policy (stopping future premiums while letting accumulated paid-up sum assured and vested bonuses mature at the end of the term), and redirecting all future annual premium savings into equity mutual funds!
- • Policy Running for 15+ Years (Near Maturity): Keep the policy active till maturity to capture the large Final Additional Bonus (FAB), which represents 20% to 30% of the total maturity cheque.
11. Visual Decision Matrix & Embeddable Financial Flowchart
To assist policyholders, certified financial planners, and personal finance researchers in selecting the right financial pathway, our actuarial team compiled the comprehensive decision architecture below:
The Definitive LIC vs BTID Selection Protocol
• NO: Stop buying endowment plans immediately. Purchase a ₹1 Crore to ₹2 Crore Pure Term Insurance policy first. Term insurance is mandatory risk management.
• YES: Proceed to Question 2.
• Under 5 Years: Neither! Use Bank Fixed Deposits, Arbitrage Funds, or Liquid Funds.
• 5 to 10 Years: Hybrid / Balanced Advantage Funds + PPF.
• 10 to 25 Years: Proceed to Question 3.
• YES: Choose BTID (Pure Term + Equity Mutual Funds SIP) for 2.2x to 2.5x higher terminal wealth.
• NO: Use Traditional LIC Endowment / PPF for forced non-discretionary savings discipline.
Content validated against Section 37, Section 28 of LIC Act 1956, Insurance Laws (Amendment) Act 2015, Section 10(10D), Section 112A, and Section 194DA of Income Tax Act 1961, IRDAI (Non-Linked Insurance Products) Regulations, and historical Nifty 50 Total Return Index (TRI) 20-year rolling performance data.