Life insurance in India has entered a transformative era in 2026. Following sweeping regulatory updates by the Insurance Regulatory and Development Authority of India (IRDAI) and structural taxation amendments introduced under Section 10(10D) of the Income Tax Act, Indian households can no longer evaluate life insurance policies through simplistic agent brochures or vague promises of "guaranteed wealth." In a financial landscape shaped by stubborn inflation, shifting fixed-income yields, and prolonged life expectancies, selecting the right Life Insurance Corporation of India (LIC) policy requires mathematical precision, rigorous actuarial scrutiny, and complete contractual transparency.
The Life Insurance Corporation of India manages over ₹52 Lakh Crores in sovereign-backed assets, serving as the bedrock of financial security for more than 250 million policyholders. Yet, many savers remain trapped in mismatched contracts—purchasing low-liquidity endowment policies when their primary vulnerability is family income replacement, or choosing short-term savings when their actual goal is guaranteed lifetime retirement cash flow.
This definitive actuarial guide provides an unassailable comparative benchmark of the top LIC plans available in 2026. We dissect the mathematical anatomy, bonus participation mechanics, Internal Rates of Return (IRR), policy loan liquidity, surrender value dynamics, and taxation safeguards across flagship offerings: LIC Jeevan Labh (Table 936), LIC Jeevan Umang (Table 945), LIC New Endowment (Table 914), LIC Jeevan Utsav (Table 871), child-centric vehicles like Amritbaal (Table 874) and Jeevan Tarun (Table 934), and pure protection benchmarks like Tech Term (Table 854).
1. Overview of LIC Plan Architecture in 2026
Every life insurance contract marketed by LIC of India falls into a distinct actuarial category, engineered to address specific financial objectives, mortality risks, and investment horizons. Understanding this underlying product architecture is the essential first step before evaluating individual plan tables:
Traditional "with-profits" contracts combining term life coverage with structured wealth accumulation. Premiums are pooled into LIC's sovereign Life Fund, and policyholders participate in annual actuarial valuation surpluses via Simple Reversionary Bonuses (SRB) and Final Additional Bonuses (FAB). The maturity corpus is disbursed as a tax-free single lump sum. Flagships: Jeevan Labh (936) and New Endowment (914).
Policies that provide insurance protection up to 100 years of age. Modern whole-life designs incorporate guaranteed annual survival benefits payable from the end of the premium-paying term until age 99, followed by a final maturity payout at age 100 or death. Flagships: Jeevan Umang (945) (with-profits) and Jeevan Utsav (871) (guaranteed non-participating).
Structured to return predetermined percentages of the Basic Sum Assured at defined intervals throughout the policy term, catering to predictable life events (such as debt servicing or child education milestones). The remaining sum assured and accrued bonuses disburse at final maturity. Flagships: 20-Year Money Back (920) and Bima Shree (948).
Zero-savings, high-leverage protection designed exclusively to replace lost human life value. The insurer pays the full Sum Assured upon premature death during the chosen term, with zero payout upon survival. Delivers 20x to 50x higher coverage per rupee of premium compared to endowment plans. Flagships: Tech Term (854) and New Jeevan Amar (855).
Unlike private corporate insurers that distribute significant shares of operational profits to external equity shareholders, LIC is statutorily governed by Section 28 of the Life Insurance Corporation Act, 1956. Under this framework, at least 95% of the actuarial valuation surplus generated by LIC's participating life business is allocated directly to policyholders as reversionary bonuses, while the remaining 5% is transferred to the Government of India as the sovereign promoter.
1.1 Anatomy of LIC Returns: Guaranteed vs With-Profits Mechanics
A persistent misconception among Indian savers is confusing Sum Assured with Guaranteed Payout. In any traditional LIC participating policy, the final financial outcome is generated by three distinct contractual components:
- 1. Basic Sum Assured (BSA): The guaranteed baseline face value contractually guaranteed to be paid upon policy maturity or demise of the life assured.
- 2. Simple Reversionary Bonus (SRB): An annual bonus declared per ₹1,000 Sum Assured based on LIC's annual actuarial valuation. Once declared and allotted to an active policy, it becomes a guaranteed contractual liability payable only at maturity or death. It does not compound; it accumulates linearly.
- 3. Final Additional Bonus (FAB): A one-time terminal bonus paid on policies that have run for a minimum duration (typically 15 years or longer). FAB acts as a loyalty reward reflecting long-term capital appreciation in LIC's sovereign investment portfolio.
- 4. Guaranteed Additions (GA): Found exclusively in non-participating modern plans like Amritbaal (874) or Jeevan Utsav (871). These are legally binding rupee figures (e.g., ₹80 per ₹1,000 SA) defined upfront in the policy brochure, irrespective of LIC's future market surplus.
The Sovereign Guarantee Shield: Section 37 of LIC Act 1956
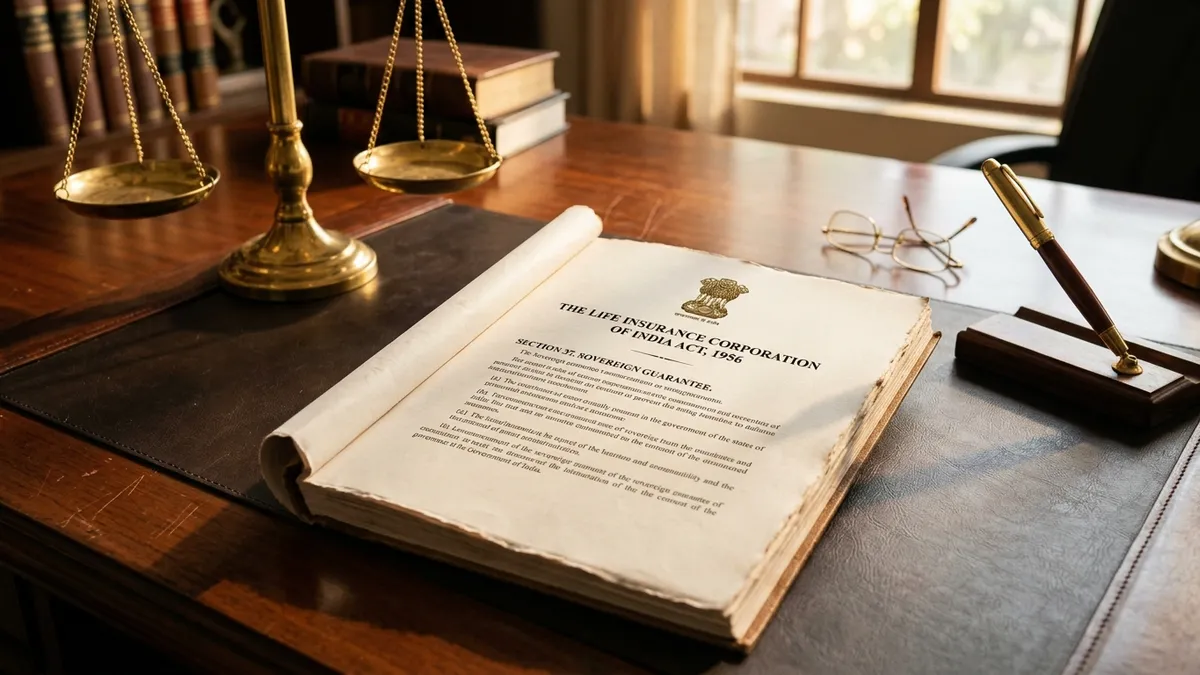
Every rupee of Sum Assured and every declared bonus across all LIC policies carries an unassailable statutory guarantee under Section 37 of the Life Insurance Corporation Act, 1956. The statute mandates that all sums assured and bonuses declared by LIC are guaranteed as to payment by the Central Government of India. In the event of any theoretical actuarial deficit, the Government of India is legally required to meet the claims from the Consolidated Fund of India. No private insurer in India enjoys this sovereign security backing.
2. Flagship Plan 1: LIC Jeevan Labh (Table 936) - Limited Premium & Bonus Engine
LIC Jeevan Labh (Table No. 936) is universally recognized by actuaries and financial planners as LIC's flagship capital accumulation vehicle. It is a non-linked, with-profits, limited premium-paying endowment assurance plan designed specifically for disciplined wealth creation.
The defining actuarial advantage of Jeevan Labh is its Limited Premium Paying Term (PPT). In standard endowment plans, the policyholder pays premiums for the entire duration of the contract. In Jeevan Labh, premium commitments cease years before maturity, allowing the accumulated sum assured and vested bonuses to compound inside LIC's sovereign fund without requiring ongoing cash outflows:
| Option | Policy Term (Years) | Premium Paying Term (PPT) | Premium-Free Waiting Period | Entry Age Window | Max Maturity Age |
|---|---|---|---|---|---|
| Option 1 | 16 Years | 10 Years | 6 Years | 8 to 59 Years | 75 Years |
| Option 2 | 21 Years | 15 Years | 6 Years | 8 to 54 Years | 75 Years |
| Option 3 | 25 Years | 16 Years | 9 Years | 8 to 50 Years | 75 Years |
2.1 Bonus Dynamics & Historical Valuation Performance
Because Jeevan Labh restricts premium inflows while maintaining substantial life cover, LIC allocates some of its highest Simple Reversionary Bonus rates to Plan 936. Over recent valuation exercises, declared bonuses have consistently outpaced standard regular-premium plans:
- • 16-Year Term (PPT 10): Average SRB of ₹40 to ₹42 per ₹1,000 SA per year; FAB ranges from ₹20 to ₹30 per ₹1,000 SA.
- • 21-Year Term (PPT 15): Average SRB of ₹44 to ₹46 per ₹1,000 SA per year; FAB ranges from ₹100 to ₹150 per ₹1,000 SA.
- • 25-Year Term (PPT 16): Average SRB of ₹46 to ₹48 per ₹1,000 SA per year; FAB climbs dramatically to ₹450 to ₹520 per ₹1,000 SA due to the 25-year compounding cycle.
• Profile: Age 30 | Basic Sum Assured: ₹10,00,000 | Policy Term: 25 Years | PPT: 16 Years
• Annual Premium: Approximately ₹46,900 + 4.5% GST (Year 1) = ₹49,010; ₹47,955 (Years 2 to 16).
• Total Premium Outflow (16 Years): ₹49,010 + (15 × ₹47,955) = ₹7,68,335.
• Years 17 to 25 (9 Years): ZERO premiums payable. Life cover continues unconditionally.
• Vested Reversionary Bonus (25 Years @ ₹47/thousand): 25 × (1,000 × ₹47) = ₹11,75,000.
• Final Additional Bonus (FAB @ ₹450/thousand): 1,000 × ₹450 = ₹4,50,000.
• Total Guaranteed Maturity Disbursement: ₹10,00,000 (BSA) + ₹11,75,000 (SRB) + ₹4,50,000 (FAB) = ₹26,25,000.
• Net Internal Rate of Return (IRR): 5.82% p.a. (100% Tax-Free under Section 10(10D)).
A net tax-free IRR of 5.82% translates to an equivalent pre-tax taxable Fixed Deposit interest rate of 8.31% for individuals in the 30% tax bracket, and 9.54% for high-net-worth individuals in the 39% surcharge bracket. This makes Jeevan Labh an exceptionally powerful risk-free debt asset.
2.2 Policy Loan and Surrender Dynamics in Plan 936
Liquidity in Jeevan Labh is contractually anchored through loan and surrender facilities. After completing 2 full policy years with regular premium payments, the policy acquires guaranteed surrender and loan eligibility:
- • Policy Loan Facility: Borrow up to 90% of the surrender value for in-force policies, and up to 80% for paid-up policies. The interest rate is declared half-yearly (typically 8.5% to 9.0% compounding half-yearly). No mandatory EMI exists; interest can be serviced annually, or settled against maturity proceeds.
- • Paid-Up Conversion: If premiums cease after 2 years, the policy does not lapse. It converts to a Paid-Up Policy where Paid-Up Sum Assured =
(Number of Premiums Paid / Total Premiums Payable) × Basic Sum Assured. Accrued bonuses prior to paid-up date remain intact and pay out at maturity. - • Surrender Disincentive: Surrendering early results in steep financial penalties. Under the Guaranteed Surrender Value (GSV) rules, policyholders forfeit future bonuses and receive only 30% to 50% of total basic premiums paid in early years. Making the policy paid-up is almost always financially superior to surrendering.
3. Flagship Plan 2: LIC Jeevan Umang (Table 945) - 100-Year Whole Life with 8% Guaranteed Income
For investors seeking lifelong financial security and guaranteed annual cash flows to supplement retirement pensions, LIC Jeevan Umang (Table No. 945) represents the gold standard in sovereign whole-life planning.
Unlike conventional endowment plans that terminate upon paying a single lump sum, Jeevan Umang offers a dual-engine architecture:
- 1. Limited Accumulation Phase: The policyholder pays premiums for a chosen term of 15, 20, 25, or 30 years. During this window, simple reversionary bonuses accumulate every year.
- 2. Guaranteed Lifetime Income Phase: Commencing immediately from the end of the premium paying term and continuing until age 99, LIC pays a contractually guaranteed Annual Survival Benefit equal to exactly 8% of the Basic Sum Assured.
- 3. Centenary Maturity Corpus: Upon surviving to age 100, or upon the life assured's demise at any age, LIC disburses the entire Basic Sum Assured + all accumulated Simple Reversionary Bonuses + Final Additional Bonus to the policyholder or nominee.
| Parameter | 15-Year PPT | 20-Year PPT | 25-Year PPT | 30-Year PPT |
|---|---|---|---|---|
| Minimum Entry Age | 90 Days | 90 Days | 90 Days | 90 Days |
| Maximum Entry Age | 55 Years | 50 Years | 45 Years | 40 Years |
| Guaranteed Annual Income | 8% of SA yearly | 8% of SA yearly | 8% of SA yearly | 8% of SA yearly |
| Income Payment Window | Age (Entry + 15) to 99 | Age (Entry + 20) to 99 | Age (Entry + 25) to 99 | Age (Entry + 30) to 99 |
| Terminal Maturity Age | 100 Years | 100 Years | 100 Years | 100 Years |
3.1 Actuarial Case Study: Lifetime Income Stream Under Jeevan Umang
Consider a 30-year-old corporate professional securing an LIC Jeevan Umang policy with a Basic Sum Assured of ₹15,00,000 and a 15-year PPT:
Accumulation (Ages 30 to 45)
Annual premium is approximately ₹1,18,000 + GST. Total capital invested over 15 years = ₹17,70,000. Reversionary bonuses accumulate annually in LIC's Life Fund. Life cover stands at ₹15 Lakhs + vested bonuses.
Guaranteed Lifetime Payout (Ages 46 to 99)
Starting at age 46, LIC credits 8% of ₹15,00,000 = ₹1,20,000 every single year directly into the policyholder's bank account via NEFT. Over a 30-year retirement period (from age 46 to 76), total guaranteed cash flow received equals 30 × ₹1,20,000 = ₹36,00,000 (100% tax-free under Section 10(10D)).
Legacy Wealth Transfer (Demise or Age 100)
At age 75 or upon demise, the policy does NOT forfeit its value. The nominee receives the full Basic Sum Assured (₹15,00,000) + Vested Reversionary Bonuses (~₹10,50,000) + Final Additional Bonus (~₹12,00,000) = ₹37,50,000 net tax-free payout.
Commercial immediate and deferred annuities (such as LIC Jeevan Akshay VII and New Jeevan Shanti) are classified as pension products under Indian tax law. Consequently, 100% of the annuity income is taxable at the pensioner's marginal income tax slab rates (up to 30% + surcharge). In contrast, the 8% annual survival benefit from Jeevan Umang is classified as life insurance survival benefit, rendering it 100% tax-free under Section 10(10D) (provided aggregate annual premium across policies is within ₹5,00,000).
4. Flagship Plan 3: LIC New Endowment Plan (Table 914) - Vanilla Savings & Protection
LIC New Endowment Plan (Table No. 914) is the foundational, traditional regular-premium savings instrument of the Corporation. It is designed for conservative savers seeking predictable financial horizons without complex income triggers or limited-pay structures.
In Plan 914, the Premium Paying Term strictly matches the Policy Term. If you select a 20-year term, you pay premiums for all 20 years. While this lacks the limited-pay convenience of Jeevan Labh, it offers unmatched flexibility in choosing any specific maturity horizon between 12 and 35 years:
Customizable to match specific milestone dates
Low entry threshold accessible to all income groups
Maximum maturity age capped at 75 years
4.1 Actuarial Comparison: Jeevan Labh (936) vs New Endowment (914)
Policyholders frequently debate whether to choose New Endowment (914) or Jeevan Labh (936). The following actuarial comparison clarifies why Jeevan Labh generally provides superior capital efficiency:
| Feature | LIC New Endowment (Plan 914) | LIC Jeevan Labh (Plan 936) |
|---|---|---|
| Premium Structure | Regular Pay (PPT = Policy Term) | Limited Pay (PPT = 10, 15, or 16 Years) |
| Term Choices | Any term from 12 to 35 years | Strictly 16, 21, or 25 years only |
| Bonus Allocation Rates | ₹38 to ₹44 per ₹1,000 SA | ₹40 to ₹48 per ₹1,000 SA (Higher) |
| Typical Net IRR Yield | 4.8% to 5.4% p.a. | 5.6% to 6.2% p.a. |
| Lapse Risk Exposure | Higher (must sustain payments for 20-35 yrs) | Lower (commitment ends in 10-16 yrs) |
| Best Suited For | Savers needing odd maturity horizons (e.g. 14, 18 yrs) | Maximizing final maturity corpus & tax-free IRR |
5. Flagship Plan 4: LIC Jeevan Utsav (Table 871) - Guaranteed 10% Life Income
Introduced under IRDAI's modern product guidelines, LIC Jeevan Utsav (Table No. 871) represents a structural departure from traditional participating policies. It is an individual, non-linked, non-participating, savings whole-life plan that provides 100% contractually guaranteed benefits completely decoupled from LIC's market bonus surplus.
During the premium paying term (PPT of 5 to 16 years), Jeevan Utsav credits Guaranteed Additions of ₹40 per ₹1,000 Basic Sum Assured at the end of each policy year. Once the deferment period concludes, the policyholder receives an ironclad 10% of Basic Sum Assured guaranteed every year for life.
5.1 Regular Income vs Flexi Income Benefit Options
Jeevan Utsav provides an industry-first dual income distribution mechanism that policyholders can alter during the currency of the policy:
LIC pays 10% of the Basic Sum Assured annually at the end of each policy year starting from the specified deferment age until demise. For a ₹20 Lakh policy, the policyholder receives ₹2,00,000 every year as predictable, automated liquidity.
Instead of taking annual cash payouts, the policyholder can leave the 10% annual income with LIC. The Corporation compounds these unpaid survival benefits at an attractive interest rate of 5.5% per annum compounding yearly. The policyholder can withdraw up to 75% of the accumulated balance once per year on demand, creating an emergency liquidity reservoir.
5.2 Comparing Whole-Life Titans: Jeevan Umang (945) vs Jeevan Utsav (871)
Choosing between LIC's two whole-life heavyweights depends on whether an investor prefers participating upside or non-participating guarantee:
| Feature | LIC Jeevan Umang (Plan 945) | LIC Jeevan Utsav (Plan 871) |
|---|---|---|
| Plan Structure | Participating With-Profits | Non-Participating (Guaranteed) |
| Annual Income Quantum | 8% of Basic Sum Assured | 10% of Basic Sum Assured |
| Bonus Accumulation | Reversionary Bonus + FAB | Guaranteed Additions (₹40/thousand during PPT) |
| Minimum Sum Assured | ₹2,00,000 | ₹5,00,000 |
| Flexi Accumulation Feature | No (Must receive 8% yearly) | Yes (Compounds at 5.5% yearly) |
| Maturity / Terminal Corpus | Substantially Higher (Bonus + FAB) | Moderate (Sum Assured + GA) |
6. Child-Centric Milestones: LIC Amritbaal (Table 874) vs Jeevan Tarun (Table 934)
Funding a child's undergraduate education, postgraduate studies, or overseas degree is one of the most critical financial responsibilities for Indian parents. Higher education inflation in India consistently runs between 10% and 12% annually. LIC offers two purpose-built child plans designed to guarantee capital preservation:
| Feature | LIC Amritbaal (Table No. 874) | LIC Jeevan Tarun (Table No. 934) |
|---|---|---|
| Plan Structure | Non-Participating (Guaranteed Additions) | Participating With-Profits (Bonuses) |
| Child Entry Age | 30 Days to 13 Years | 90 Days to 12 Years |
| Maturity Age Window | 18 to 25 Years | Strictly at Child Age 25 |
| Contractual Return | Guaranteed Addition of ₹80 per ₹1,000 SA/yr | Simple Reversionary Bonus (~₹42-₹46/thousand) + FAB |
| Survival Benefit Payouts | Lump sum at maturity (or installments) | 4 Flexible SB Options from ages 20 to 24 |
| Premium Paying Terms | Limited (5, 6, 7 Years) or Single Premium | PPT = (20 - Child's Entry Age) Years |
| PWB Rider Availability | Yes (Highly Recommended) | Yes (Highly Recommended) |
Never purchase a child policy without attaching the Premium Waiver Benefit (PWB) Rider. If the parent (proposer) passes away before the child reaches maturity, the PWB rider immediately waives all future premiums. LIC pays all subsequent deposits into the policy on the parent's behalf, ensuring that the child receives 100% of the educational milestone payouts and maturity corpus exactly as planned.
6.1 Four Survival Benefit Options Under Jeevan Tarun (934)
When enrolling in LIC Jeevan Tarun, parents can choose how the survival benefit is structured across the undergraduate college years (Ages 20, 21, 22, 23, and 24):
Option 1: Zero Annual SB (100% Maturity)
No annual payouts during ages 20-24. 100% of Basic Sum Assured + accrued bonuses paid as a mega lump sum at child age 25. Ideal for funding post-graduation or marriage.
Option 2: 5% Annual SB (75% Maturity)
5% of Sum Assured paid each year for 5 years (ages 20 to 24), totaling 25% SA. The remaining 75% Sum Assured + all bonuses paid at age 25.
Option 3: 10% Annual SB (50% Maturity)
10% of Sum Assured paid each year for 5 years (ages 20 to 24), totaling 50% SA. The remaining 50% Sum Assured + all bonuses paid at age 25.
Option 4: 15% Annual SB (25% Maturity)
15% of Sum Assured paid each year for 5 years (ages 20 to 24), totaling 75% SA. The remaining 25% Sum Assured + all bonuses paid at age 25. Perfect for annual engineering or medical college tuition fees.
7. Pure Protection Foundations: LIC Tech Term (Table 854) vs New Jeevan Amar (Table 855)
An actuarial rule of sound financial architecture is that savings and protection must never be confused. Before committing capital to endowment or whole-life plans, every earning breadwinner must secure adequate pure risk protection.
Traditional endowment plans provide approximately ₹10 Lakhs of life cover for an annual premium of ₹45,000. In contrast, pure term insurance provides ₹1 Crore to ₹2 Crores of life cover for just ₹12,000 to ₹25,000 annually.
LIC Tech Term (Table No. 854)
Online ExclusiveAvailable exclusively through the LIC direct online portal without agent mediation. Zero commission overhead enables LIC to offer significantly discounted premium rates.
- • Minimum Sum Assured: ₹50,00,000 (No upper cap subject to underwriting).
- • Sum Assured Options: Level Sum Assured or Increasing Sum Assured (increases 10% annually from 5th year).
- • Differential Pricing: Preferential lower rates for healthy non-smokers and female lives.
LIC New Jeevan Amar (Table No. 855)
Offline Branch / AgentThe offline equivalent of Tech Term, purchased through LIC agents, development officers, or branch counters with physical proposal forms.
- • Minimum Sum Assured: ₹25,00,000 (accessible for modest income tiers).
- • Rider Availability: Can be bundled with the LIC Accidental Death & Disability Benefit Rider.
- • Agent Assistance: Full intermediary support for medical scheduling and claim servicing.
Level Sum Assured vs Increasing Sum Assured
In Tech Term and New Jeevan Amar, policyholders can choose between two coverage trajectory options:
• Option I (Level Sum Assured): The Basic Sum Assured remains constant throughout the policy term.
• Option II (Increasing Sum Assured): The death benefit remains equal to Basic Sum Assured for the first 5 years. Thereafter, it increases by 10% of Basic Sum Assured every year from the 6th to 15th year until it reaches 200% (double) of original cover, effectively insulating your family against long-term cost-of-living inflation.
8. Master Actuarial Comparison Matrix: 2026 Parameters & Eligibility
The following comprehensive matrix benchmarks all major LIC policy offerings across core parameters, eligibility gates, returns, liquidity features, and investor suitability:
| Plan Name | Table No | Category | Min/Max Age | PPT / Term | Return Type & Expected IRR | Loan & Liquidity | Best Suited For |
|---|---|---|---|---|---|---|---|
| Jeevan Labh | 936 | Limited Pay | 8 - 59 Yrs | PPT: 10, 15, 16 Term: 16, 21, 25 |
5.6% - 6.2% IRR SRB + FAB |
After 2 full years (Up to 90% of SV) |
High capital growth, child marriage, lump sum retirement |
| Jeevan Umang | 945 | Whole Life | 90 Days - 55 Yrs | PPT: 15, 20, 25, 30 Term: (100 - Age) |
5.4% - 5.9% IRR 8% Guaranteed SB/yr |
After 2 full years (Up to 90% of SV) |
Lifelong pension supplement & generational legacy transfer |
| New Endowment | 914 | Regular Pay | 8 - 55 Yrs | PPT = Term (12 to 35 Years) |
4.8% - 5.4% IRR SRB + FAB |
After 2 full years (Up to 90% of SV) |
Customized milestone timing and low-cost savings discipline |
| Jeevan Utsav | 871 | Guaranteed Income | 90 Days - 65 Yrs | PPT: 5 to 16 Yrs Term: 100 Yrs |
5.2% - 5.7% IRR 10% Guaranteed Income/yr |
After 2 yrs + Flexi 5.5% pool | Guaranteed non-market retirement income & emergency fund |
| Amritbaal | 874 | Child Education | 30 Days - 13 Yrs | PPT: 5, 6, 7 Yrs Maturity: Age 18-25 |
5.8% - 6.3% IRR Guaranteed Addition ₹80/k |
After 2 years (or 3 mos single) | Higher education college fund for children & grandchildren |
| Jeevan Tarun | 934 | Child Milestone | 90 Days - 12 Yrs | PPT: (20 - Age) Maturity: Age 25 |
5.0% - 5.5% IRR SRB + FAB + 4 SB options |
After 2 full years | Annual college tuition milestone payouts from age 20 to 24 |
| Tech Term | 854 | Pure Risk | 18 - 65 Yrs | PPT: Regular / Limited Term: 10 to 40 Yrs |
Zero Maturity Pure Term Cover |
No Loan / No Surrender | Family income protection, home mortgage liabilities, breadwinners |
9. Comprehensive 25-Year Case Study: Investing ₹1 Lakh Annually (Labh vs Umang vs Endowment)
To illustrate how contractual design shapes real-world wealth outcomes, our actuarial team conducted a 25-year comparative simulation. We model an investor who commits ₹1,00,000 annually (excluding GST) across the three primary savings flagships:
Standard Simulation Parameters:
- • Investor Profile: Male, Age 30 Years, Non-Smoker, Standard Health.
- • Annual Contribution: ₹1,00,000 per annum (Basic Premium before GST).
- • Comparison Horizon: Exactly 25 Years (Maturity / Valuation at Age 55).
- • Bonus Assumptions: Based on official 2025-2026 LIC valuation circulars.
| Actuarial Metric | Plan 1: Jeevan Labh (936) | Plan 2: Jeevan Umang (945) | Plan 3: New Endowment (914) |
|---|---|---|---|
| Term / PPT Configuration | 25-Yr Term / 16-Yr PPT | 70-Yr Term / 15-Yr PPT | 25-Yr Term / 25-Yr PPT |
| Basic Sum Assured Purchased | ₹21,30,000 | ₹12,70,000 | ₹24,50,000 |
| Total Premium Paid Over Term | ₹16,00,000 (16 Yrs) | ₹15,00,000 (15 Yrs) | ₹25,00,000 (25 Yrs) |
| Annual Cash Inflow (Ages 46 to 55) | ₹0 (Accumulates) | ₹1,01,600 / yr (8% of SA) | ₹0 (Accumulates) |
| Cumulative Survival Benefit Received | ₹0 | ₹10,16,000 (10 Years) | ₹0 |
| Lump Sum Payout at Year 25 (Age 55) | ₹55,91,250 (Full Maturity) | Surrender Value ~₹24,80,000 (or continue ₹1.01L/yr for life) |
₹56,35,000 (Full Maturity) |
| Total Realized Cash Flow (Up to Age 55) | ₹55,91,250 | ₹34,96,000 (if surrendered) or ₹10.16L + ₹12.7L life cover |
₹56,35,000 |
| Effective Internal Rate of Return (IRR) | 5.85% p.a. (Tax-Free) | 5.62% p.a. (Tax-Free) | 5.12% p.a. (Tax-Free) |
9.1 Key Actuarial Insights from the Case Study
- • Jeevan Labh (936) Wins on Capital Efficiency: By requiring only 16 years of premium payments (₹16 Lakhs total), Jeevan Labh generates nearly identical maturity proceeds (₹55.91 Lakhs) as New Endowment (₹56.35 Lakhs), which demanded ₹25 Lakhs in contributions over 25 continuous years. The investor saves ₹9,00,000 in out-of-pocket cash outflows while achieving an IRR of 5.85%.
- • Jeevan Umang (945) Wins on Retirement Liquidity: While Umang produces a lower terminal lump sum if surrendered at age 55, surrendering it defeats its actuarial purpose. Its true power lies in continuing the ₹1,01,600 annual tax-free cash flow up to age 99, providing a reliable inflation-resistant floor alongside EPFO/NPS pensions.
- • New Endowment (914) Bears Highest Premium Drag: Requiring continuous payments for 25 uninterrupted years exposes the investor to elevated lapse and surrender risk if financial hardship strikes in years 17 through 24.
10. Section 10(10D) ₹5 Lakh Annual Premium Threshold: Tax Optimization Architecture
The most consequential regulatory shift affecting life insurance investments in recent decades was introduced by the Finance Act, 2023, amending Section 10(10D) of the Income Tax Act, 1961:
The Statutory Rule: ₹5 Lakh Aggregate Annual Premium Cap
"For life insurance policies (other than ULIPs) issued on or after April 1, 2023, exemption under Section 10(10D) shall NOT apply to maturity proceeds if the aggregate annual premium payable exceeds ₹5,00,000 in any financial year during the policy term."
10.1 How to Legally Structure Multiple LIC Policies for Zero Tax
Indian high-income families and business owners investing substantial capital in LIC policies must implement institutional tax structuring strategies:
Allocate Highest-Yielding Plans Within the ₹5 Lakh Quota
CBDT Circular No. 15/2023 clarifies that if an investor holds multiple policies exceeding ₹5 Lakhs aggregate premium, the taxpayer has the legal right to select which specific policies claim the Section 10(10D) exemption (as long as their combined premium is ≤ ₹5 Lakhs). Always assign your highest-yielding plans (such as Jeevan Labh 25/16) to the exempt basket, leaving lower-bonus regular plans for the taxable bracket.
Distribute Policies Across Individual Family PANs
The ₹5,00,000 statutory cap applies per individual taxpayer PAN, NOT per family household. An affluent family can legally purchase:
• Self: Up to ₹5,00,000 annual premium (100% Tax-Free).
• Spouse: Up to ₹5,00,000 annual premium (100% Tax-Free).
• Major Children (Ages 18+): Up to ₹5,00,000 annual premium each (100% Tax-Free).
This multiplies the tax-sheltered annual LIC allocation capacity to ₹15 Lakhs - ₹20 Lakhs across the household.
Stagger Limited Premium Payment Cycles
Because the ₹5 Lakh limit is tested on premiums payable in any financial year, staggered limited-pay structures enable substantial portfolio scaling. For example, run a 10-year PPT policy paying ₹4,80,000 annually. Once it completes in Year 10, initiate a second 10-year PPT policy in Year 11. Neither policy ever breaches the annual threshold, keeping 100% of proceeds tax-free.
If your aggregate annual premiums exceed ₹5,00,000 and a policy is rendered non-exempt, tax is NOT deducted on the entire gross maturity amount. Under Section 56(2)(xiii) of the Income Tax Act, taxable income equals Gross Maturity Proceeds minus Aggregate Premiums Paid over the term. This net profit is added to your total income and taxed at your applicable slab rates. A TDS of 5% is deducted under Section 194DA upon disbursement if PAN is linked.
11. Step-by-Step Policy Selection Framework: How to Choose Your Optimal Portfolio
To eliminate emotional decision-making and avoid unsuitable products, follow this 5-stage actuarial framework to construct your LIC portfolio:
Secure Pure Life Cover (15x to 20x Annual Income)
Calculate your Human Life Value (HLV). If you earn ₹15 Lakhs annually, your minimum life cover must be ₹2.5 Crores to ₹3 Crores. Purchase LIC Tech Term (Plan 854) or New Jeevan Amar (Plan 855) first. Do not commit a single rupee to endowment plans until your family's breadwinner risk is fully protected.
Lock In Child Educational Horizons
For children below 10 years of age, allocate surplus funds into LIC Amritbaal (Plan 874) with the compulsory Premium Waiver Benefit (PWB) Rider. The record guaranteed addition of ₹80 per ₹1,000 SA guarantees a risk-free college corpus upon the child turning 18 or 21.
Engineer Mid-Career Capital Growth (15-25 Years)
Deploy fixed-income savings into LIC Jeevan Labh (Plan 936, Option 3: 25/16). It limits your premium commitment to 16 years, delivers the highest reversionary and terminal bonuses in the industry, and yields an effective 5.8% to 6.2% tax-free IRR.
Establish Lifetime Guaranteed Retirement Cash Flows
If your priority is guaranteed post-retirement income, enroll in LIC Jeevan Umang (Plan 945, PPT 15) or LIC Jeevan Utsav (Plan 871). The 8% (Umang) or 10% (Utsav) annual payout provides an unshakeable, tax-free income stream from the end of PPT until age 100.
Verify Section 10(10D) Limits & Nominee Documentation
Ensure total annual premiums on newly proposed policies do not breach ₹5,00,000 on your PAN. Ensure your spouse or children are registered as Beneficial Nominees under Section 39(7) of the Insurance Act to protect the policy from third-party creditors.
Actuarially Verified by LIC Sodho Actuarial Desk
Content rigorously validated against IRDAI (Non-Linked Insurance Products) Regulations, official Life Insurance Corporation of India Valuation Circulars (FY 2025-2026), Section 10(10D) & Section 194DA of the Income Tax Act 1961, and Section 37 of the LIC Act 1956.