LIC Whole Life Insurance: Architecture of 100-Year Wealth & Protection
Traditional life insurance contracts in India typically mature when the policyholder turns 55, 60, or 65 years of age. While this provides a timely maturity payout at retirement, it leaves the individual completely uninsured during their elder years—precisely when health vulnerabilities peak and the desire to leave an estate for descendants is strongest.
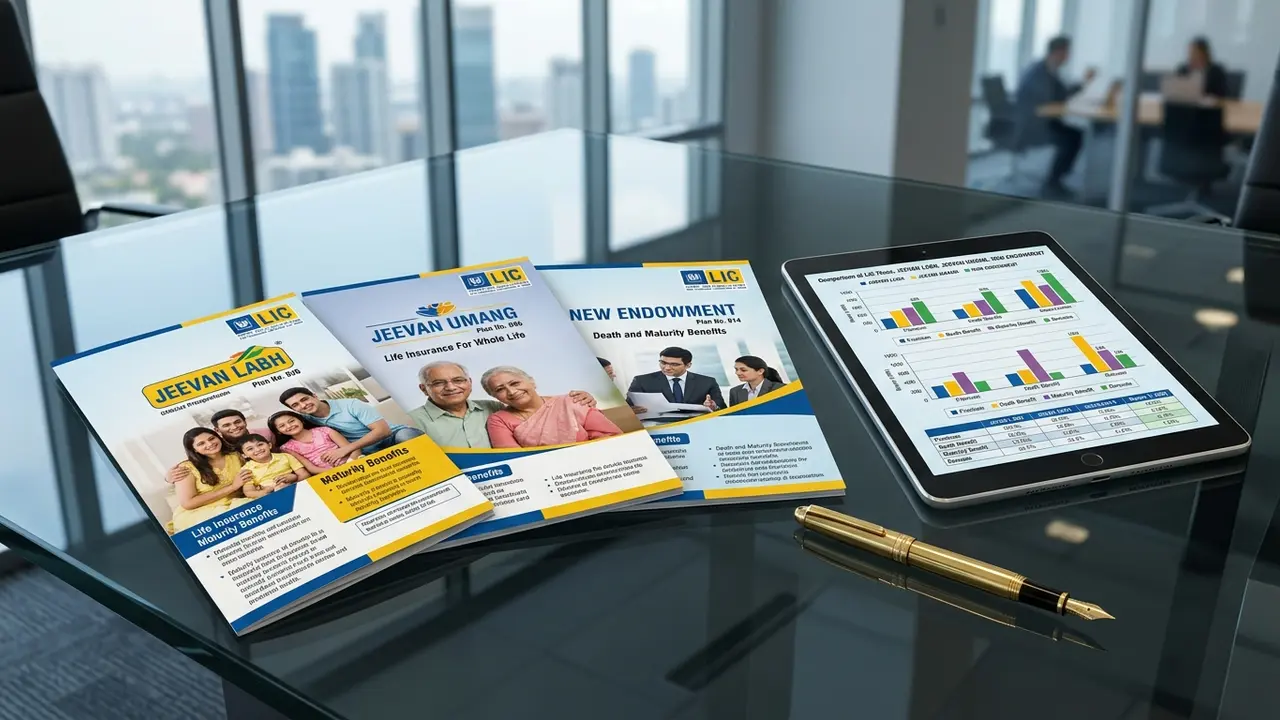
The Life Insurance Corporation of India addresses this critical gap through its flagship Whole Life Insurance contracts: LIC Jeevan Umang (Table No. 945) and LIC Jeevan Utsav (Table No. 871). These plans provide an unbreakable risk shield lasting up to 100 years of age, coupled with contractually guaranteed lifetime annual cashflows.
Head-to-Head Comparison: Jeevan Umang vs. Jeevan Utsav
| Parameter | LIC Jeevan Umang (Plan 945) | LIC Jeevan Utsav (Plan 871) |
|---|---|---|
| Plan Structure | Participating, With-Profits | Non-Participating, Guaranteed |
| Annual Survival Income | 8% of Basic Sum Assured | 10% of Basic Sum Assured |
| Bonus Mechanism | Simple Reversionary Bonus + High FAB | Guaranteed Additions (₹40/₹1,000 SA in PPT) |
| Premium Paying Terms | 15, 20, 25, or 30 Years | 5 to 16 Years |
| Minimum Sum Assured | ₹2,00,000 | ₹5,00,000 |
| Tax Treatment | 100% Tax-Free (Sec 10(10D)) | 100% Tax-Free (Sec 10(10D)) |
Inter-Generational Wealth Creation & HUF Planning
Building an Untouchable Family Legacy
Whole life policies serve as an exceptional legal shelter under Hindu Undivided Family (HUF) and Married Women's Property Act (MWPA) frameworks. The annual 8% or 10% survival benefits can fund lifestyle and medical expenses throughout the policyholder's senior years. When death occurs, the tax-free death claim (Basic Sum Assured + accumulated additions) passes straight to children and grandchildren without undergoing probate court delays.
Statutory GST & Income Tax Exemption (FY 2026-27)
GST Application Rules
- Year 1 Premium: 4.5% statutory GST (2.25% CGST + 2.25% SGST).
- Year 2 Onwards: 2.25% statutory GST (1.125% CGST + 1.125% SGST).
Section 80C & Section 10(10D)
Premiums qualify for tax deductions up to ₹1,50,000 under Section 80C. All annual survival cashflows (8% or 10%) and age-100 maturity or demise payouts are 100% tax-free under Section 10(10D).
Frequently Asked Questions (FAQ)
What is the difference between LIC Jeevan Umang (Plan 945) and Jeevan Utsav (Plan 871)?
LIC Jeevan Umang (Plan 945) is a participating whole life plan offering an 8% annual survival benefit plus annual Simple Reversionary Bonuses and FAB up to age 100. LIC Jeevan Utsav (Plan 871) is a non-participating plan offering a higher 10% guaranteed annual survival benefit, backed by Guaranteed Additions of ₹40/₹1,000 SA during the premium paying term.
How long does coverage last in LIC Whole Life policies?
Both Jeevan Umang and Jeevan Utsav provide active death protection until the policyholder reaches 100 years of age, ensuring an enduring tax-free legacy for children, grandchildren, or nominees.
Are whole-life annual survival payouts taxable in India?
No. Under Section 10(10D) of the Income Tax Act, 1961, all annual survival payouts (whether 8% in Umang or 10% in Utsav) and age-100 maturity or death claims are 100% tax-free, provided policy conditions are met.
What happens if the policyholder survives to Age 100?
At Age 100, the policy matures. The policyholder receives the Basic Sum Assured along with all accumulated Simple Reversionary Bonuses and Final Additional Bonus (or accumulated Flexi fund balance in Jeevan Utsav).
Can I avail a policy loan against an LIC Whole Life policy?
Yes, policy loans are available after completing at least 2 full years of premium payments, allowing policyholders to borrow up to 90% of the surrender value for emergency liquidity without terminating their lifelong cover.
Case Study: 30-Year-Old Creating an Untouchable ₹25 Lakh Legacy
Consider a 30-year-old opting for a ₹25,00,000 Sum Assured policy under Jeevan Umang (Plan 945) with a 20-year PPT:
- Premium Payment Phase (Age 30 to 50): Pays annual premiums eligible for Section 80C deductions. Accrues annual Simple Reversionary Bonuses for 20 years.
- Lifetime Cashflow Phase (Age 50 to 99): Receives guaranteed 8% annual survival payouts of ₹2,00,000 every single year tax-free. Over 40 years of retirement, this totals ₹80,00,000 in direct cashflow!
- Age 100 Maturity / Demise Legacy: Nominees receive the full ₹25,00,000 Basic Sum Assured + 20 years of vested bonuses + substantial Final Additional Bonus—delivering an inheritance of ₹1.5+ Crores tax-free under Section 10(10D).